

A $75,000 shipment of premium fabric arrives on time—with no visible damage. But when opened, half is ruined by water stains. The "all risk" policy denies the claim. Why?
This scenario is a costly lesson in cargo insurance realities. Many businesses assume they’re fully covered—until disaster strikes. This guide debunks the biggest myths, so you don’t learn the hard way.
The Foundation: What Cargo Insurance Is
Cargo insurance protects against physical loss or damage to goods during transit. It's governed by principles of maritime law, and its primary function is to transfer risk from the cargo owner to an insurer.
However, a policy is not a blanket guarantee. It's a specific contract that covers only defined risks while explicitly excluding others. The key is knowing which is which.
Myth 1: "All Risk" Means Everything Is Covered
Reality: "All Risk" Actually Means "All Excluded Risks"
The term "all risk" is misleading. A better name? "All perils—except the ones we listed." These policies cover physical loss or damage unless the cause is specifically excluded.
Case Study: The $200,000 Smartphone Shipment That Wasn’t Covered
A distributor shipped phones from Shenzhen to Miami. They arrived intact—but extreme heat during port delays degraded the batteries, making them worthless. The claim was denied: no external damage = inherent vice exclusion.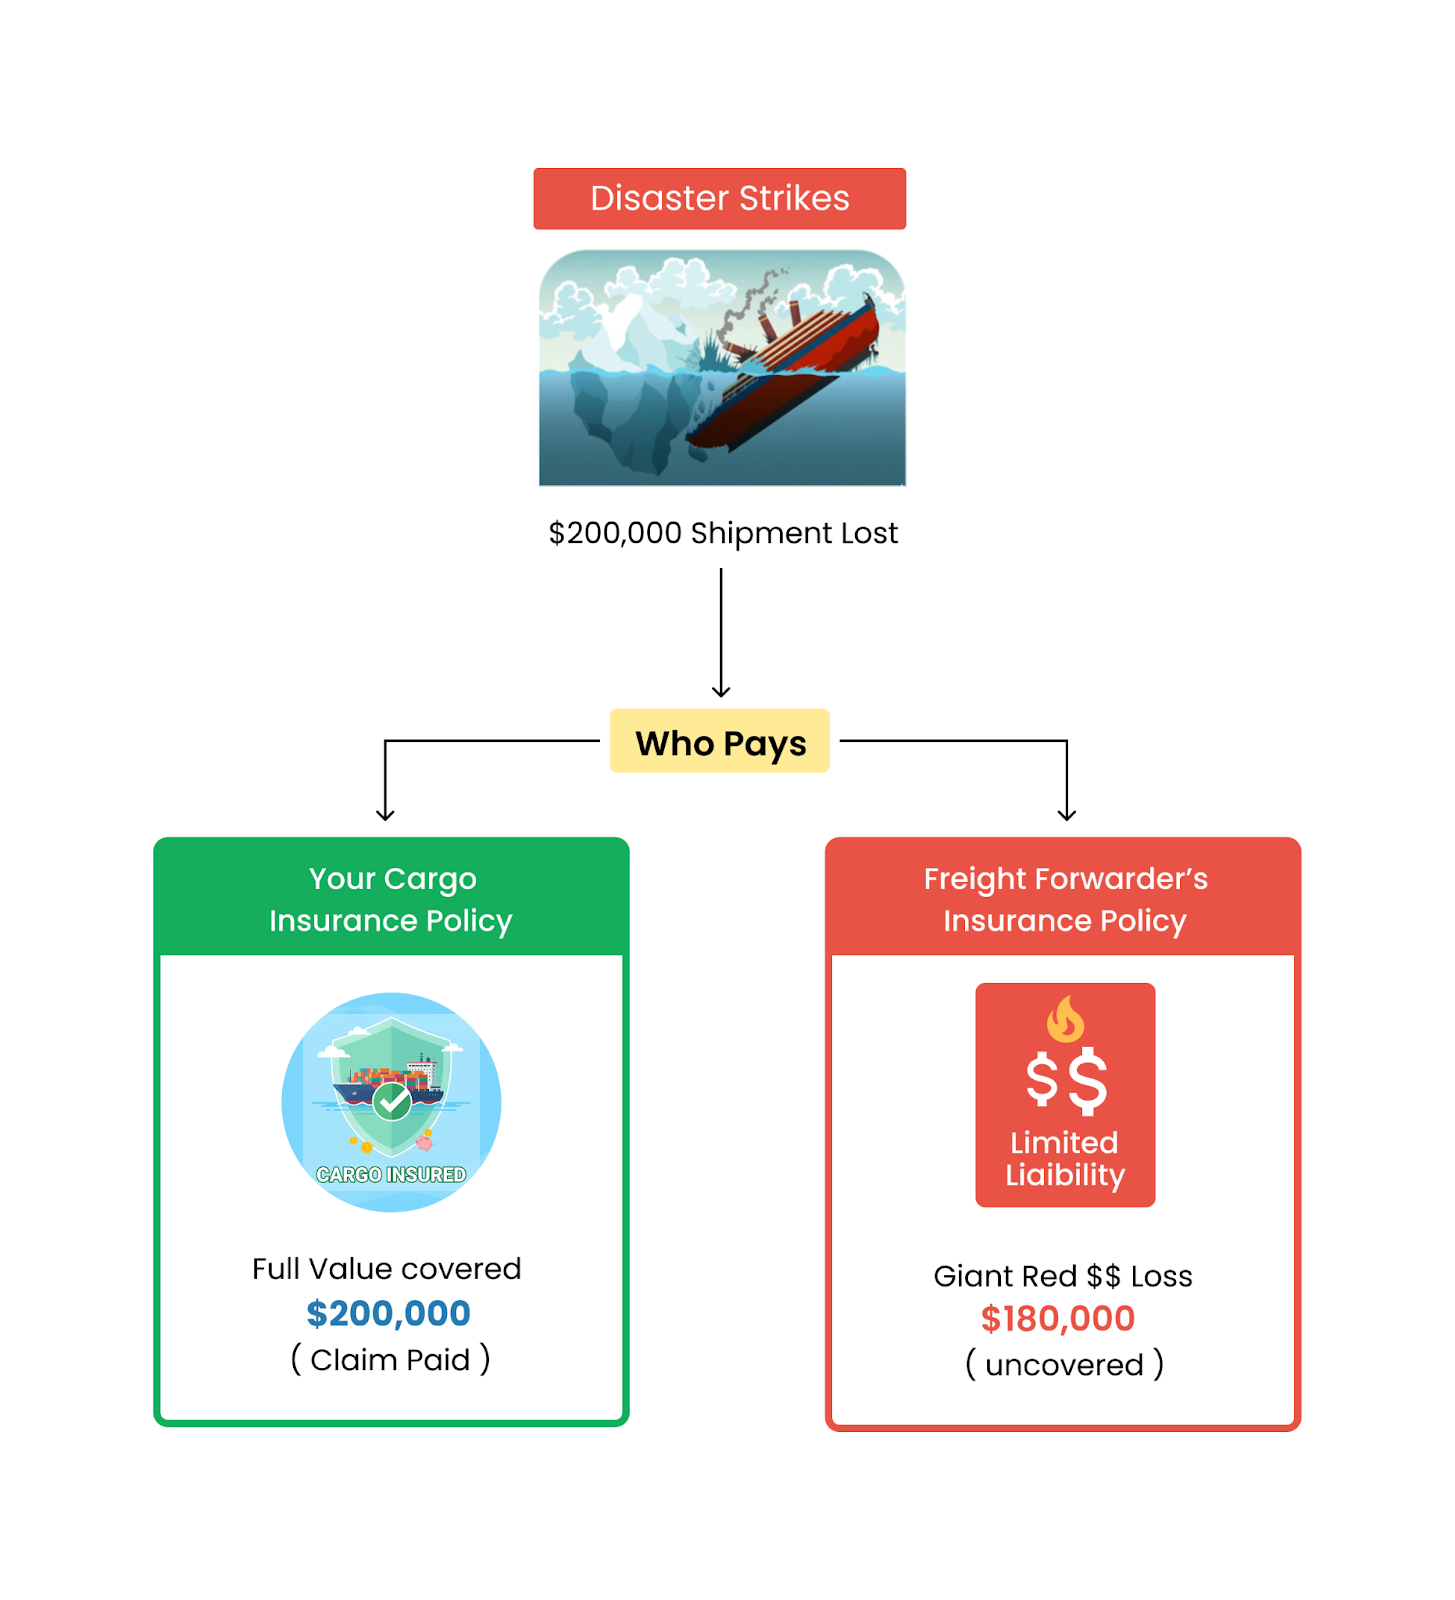
Common "All Risk" Exclusions:
Inherent Vice: Loss caused by the nature of the goods themselves (e.g., fruit rotting, metal rusting, fabric condensation).
Ordinary Leakage/Wear and Tear: Normal losses expected during transit.
Loss Due to Delay: Financial or physical losses where the proximate cause is a delay.
Improper Packing: Damage resulting from insufficient or inadequate packing by the shipper.
Acts of War, Strikes, Riots & Civil Commotions (SR&CC): These are typically excluded but can be covered with a specific endorsement.
Mysterious Disappearance: A loss discovered at inventory check with no evidence of theft.
Key Takeaway: Your policy’s exclusions page is more important than its coverage page. Read it first.
Myth 2: Your Freight Forwarder's Insurance Covers Your Cargo
Reality: Their Policy Protects Them—Not You
Freight forwarders carry liability insurance, not full cargo coverage. Their responsibility is often capped at:
$0.50 per pound (U.S. domestic)
$500 per package (COGSA for international)
Case Study: The Warehouse Fire That Cost $180,000
A $200,000 machinery shipment was destroyed in a forwarder’s warehouse fire. The shipper assumed full coverage—but received only $20,000 under the forwarder’s liability limits.
Forwarders operate under established liability frameworks, including:
FIATA (International Federation of Freight Forwarders Associations) terms
BIFA (British International Freight Association) conditions
Federal Maritime Commission (FMC) regulations for NVOCCs
Key Takeaway: Never rely on a third party’s insurance. Secure your own first-party policy for full-value coverage.
Myth 3: Loading and Unloading Damage Is
Automatically Covered
Case Study 1: The $2M Sunk Machinery Claim
A German manufacturer shipped heavy machinery to Brazil via ocean freight. Mid-voyage, the vessel collided with debris, flooding the cargo hold. The machinery was submerged in saltwater for 48 hours before salvage.
The shipper’s "All Risk" claim was denied—because the policy excluded "mechanical breakdown of the vessel." The fine print considered the collision a "latent defect" in the ship’s navigation systems, not an external peril.
Lesson:
"All Risk" doesn’t cover carrier equipment failures.
Demand "marine perils" endorsements for high-value shipments.
Case Study 2: The Perfume That Turned to Vinegar
A French exporter shipped luxury perfume to Dubai in a temperature-controlled container. The cooling system failed in transit, causing the fragrance to chemically degrade. The insurer denied the claim, arguing:
No visible damage (liquid was still bottled).
Inherent vice (perfume’s sensitivity to heat).
The shipper won by proving:
The carrier’s temperature logs showed 46°C for 72 hours (breach of contract).
Lab tests confirmed irreversible chemical changes.
Key Takeaway:
IoT sensors + contractual SLAs save claims.
"No physical damage" denials can be fought with scientific evidence.
Reality: Proving Fault Is a Battle—And Insurers Will Fight It
Claims for loading/unloading damage hinge on:
Negligence: Was the crane operator properly trained? Did the port ignore a known equipment issue?
Custody and Control: When/where did damage occur? Different policy clauses apply.
Third-Party Liability: Can the insurer recover costs from the port/trucker?
Key Takeaway
Document Everything.
Photograph damaged goods + package immediately
Get witness statements if possible.
FAQ: Quick Answers to Common Cargo Insurance Questions
Q: How can I prove loading damage for a claim?
A: Time-stamped photos, signed inspection reports, and witness statements are critical. Never sign a clean receipt if damage exists.
Q: Does "All Risk" cover theft?
A: Only if there’s evidence of forced entry. "Mysterious disappearance" (no proof of theft) is usually excluded.
Q: Can I get coverage for inherent vice?
A: Rarely. Some specialized insurers offer limited protection, but exclusions often apply. Proper packaging and transit controls are your best defense.
Coming in Part 2:
We’ll dismantle more myths, including:
Why "delay coverage" isn’t what you think
Theft vs. mysterious disappearance—the fine line
General Average: The ancient rule that could sink your profits
Want full protection? Don’t guess - read Part 2 before your next shipment.
Get a quote for your shipment
Have a shipment to move? Send the origin, the destination, the cargo and the container or weight; we reply with the rate, the routing and the services included.